
I opened my first credit card at 18 with one of Canada's big banks.
$1,000 limit.
I still have it. Still $1,000.
Every few months, a notice shows up offering to bump it to $1,500. Generous. But it isn't my primary bank. They see one card. They know nothing else about me, so the number stays the same.
I thought about that card a lot while moderating "Where Credit Goes Next" at the Canadian Lenders Summit in Toronto last week. I was joined by three people who build lending products for a living: Matthew Wiens (Senior Vice President of Bank Programs and Legal Affairs at Propel Holdings), Cato Pastoll (Co-Founder and CEO of Loop), and Casey Lewis (Director of Product at Wealthsimple).
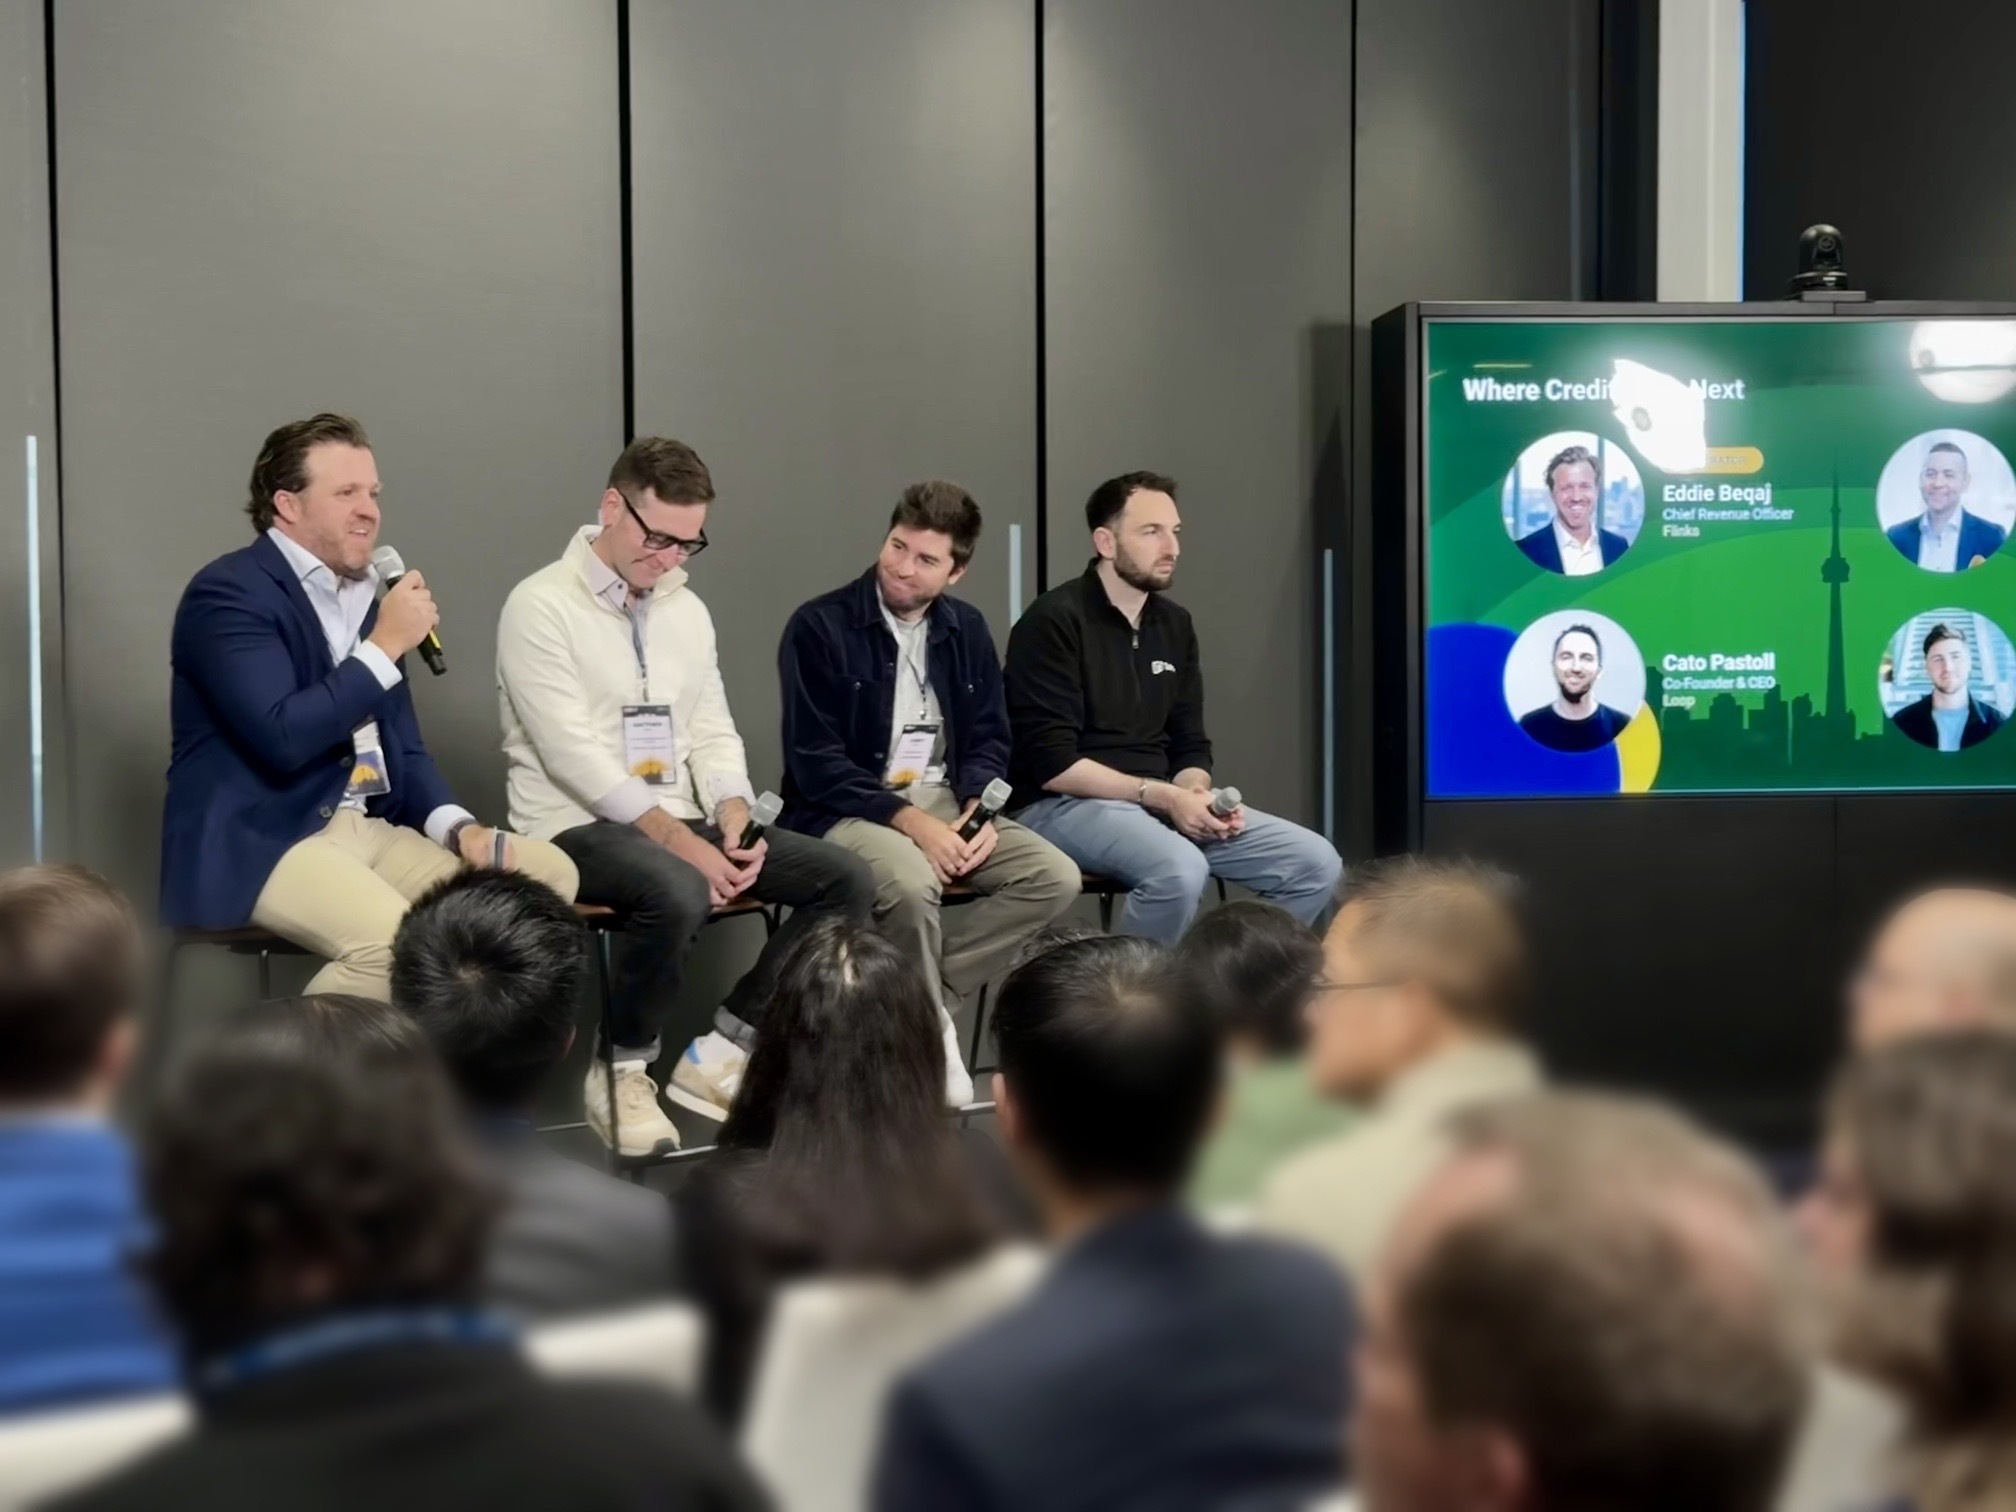
Different companies. Different customers. Same challenges.
A great customer, on paper a terrible bet
One panelist told a story that stuck with me. While researching a market, he applied for loans from nearly every lender in it, and his credit score took a serious hit. He’s a senior executive with real assets, and he still couldn’t get a credit card.
On paper, a terrible bet. Look at his actual finances, and it’s hard to find the risk.
He argues that traditional models lean heavily on history, a question lenders often don’t need answered. Cash flow underwriting looks ahead, which broadens who can get credit.
Same story, bigger numbers
Cato sees it in small business every day. Picture a company doing around $5 million in revenue, with a few hundred thousand dollars in EBITDA. Its owner holds a personal credit card with a $10,000 limit.
My $1,000 and that $10,000 are the same story.
Cato's explanation: the data sources are homogeneous. Same inputs, over and over, so the same answers come out. At Loop, they look at customers' cash flow where they bank with Loop. Where they don't, they've built data integrations that let them rebuild a company's P&L, revenue and expenses included. In his view, offering a $10,000 limit to a $5 million business fails to set anyone apart from the existing market.
What you can see changes what you can offer
Casey described the same shift from the consumer side. Wealthsimple underwrites directly against a customer's total holdings. For example, their portfolio line of credit assesses assets dynamically—recognizing that a concentrated bet and a diversified portfolio carry very different risks
The result: Wealthsimple has been able to scale faster and extend higher limits to customers earlier.
More visibility, more credit, sooner.
More data can make it worse
I pushed Matt on the flip side. When does more data hurt?
His answer came from experience. Propel looks at over 1,000 data points on each customer. At that volume, two data points can conflict and produce a false positive. The fix he described is a learning model built by a co-founder who worked on one of the early AI underwriting models. It takes in market conditions, cash flow, even where an applicant is applying from compared with their IP address, then keeps updating against performance.
A credit decision can't be a moment in time, he said. The world changes. Gig work is growing. People's circumstances shift.
What I took away
One: lenders who see more of a person's financial life make better offers, and they make them faster.
Two: the data has to be right. Conflicting signals produce false positives. Stale information produces decisions about a person who no longer exists. A bigger pile of data helps only if it's accurate and current.
That's where I'll admit my bias. I said it on stage, and I'll say the obvious here: I work at Flinks. We're the embedded finance platform lenders use to connect, with the applicant's consent, to bank accounts at more than 15,000 financial institutions, so the cash flow, balances, and income behind a decision come directly from the account.
Which brings me back to my $1,000.
Somewhere, a lender could look at years of how I actually manage money and offer something far better than an automated bump to $1,500. The data exists. The question is who gets to see it, and whether they can trust what they see.